Diesel and product cracks still flash war-risk stress
Refined-product markets, especially diesel, remain sensitive to Middle East risk even when crude consolidates. Europe’s product balance is part of the autumn story on the public market record, according to the latest multi-outlet reporting.
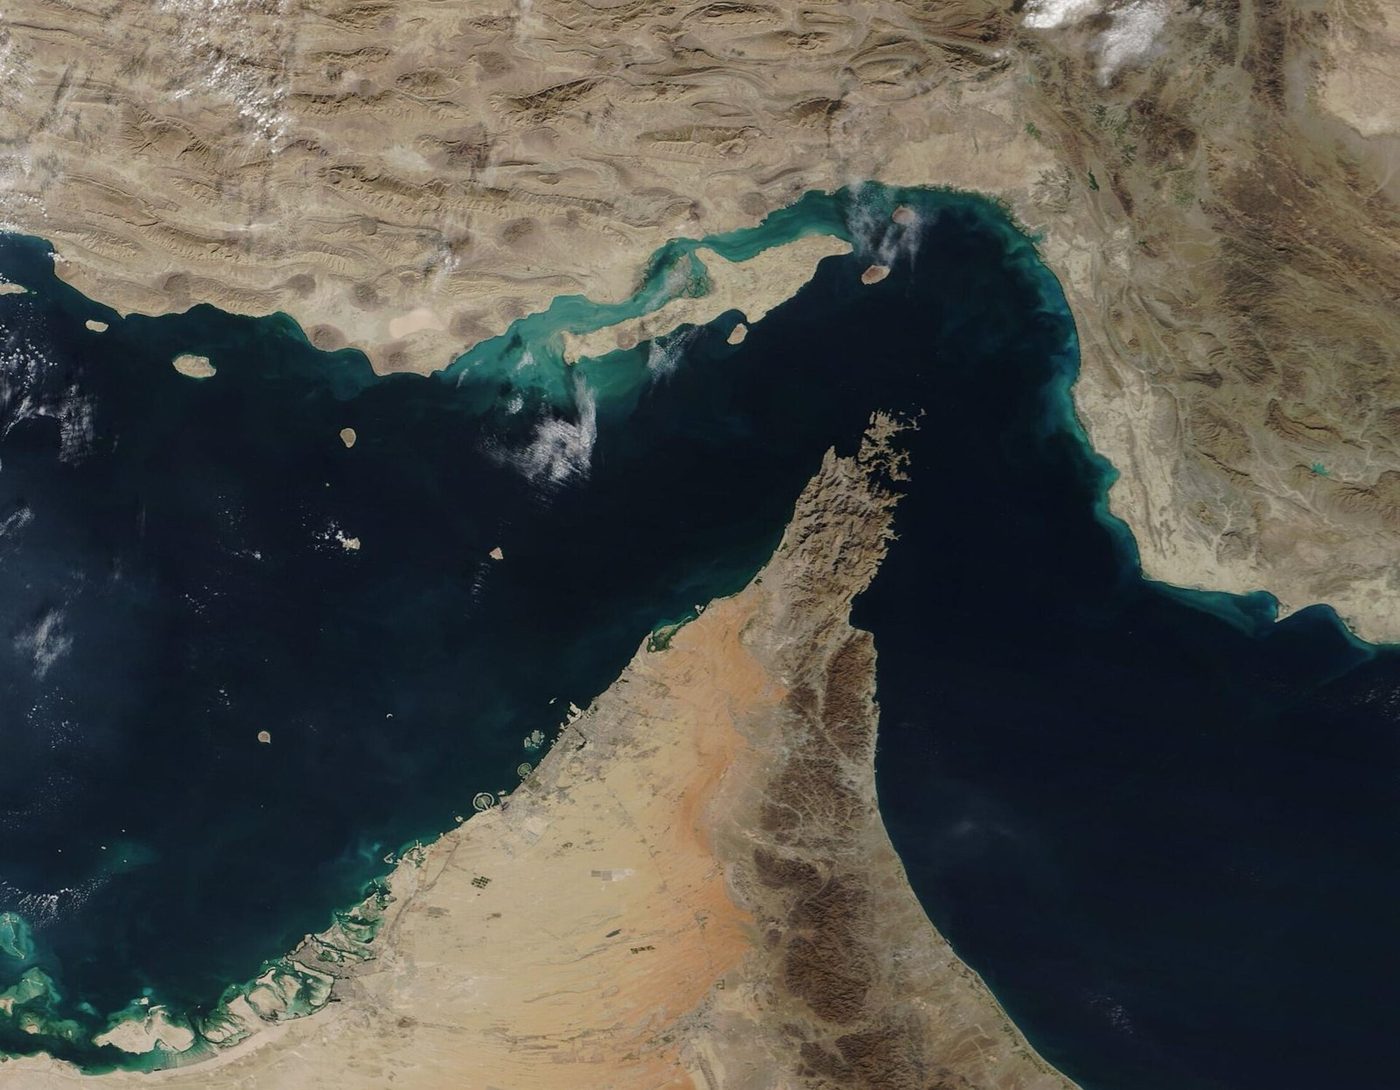
Diesel and middle-distillate cracks remain a business-desk tell for Iran war stress even when crude futures consolidate on a given session. Market wraps into Q4 flagged diesel and geopolitics alongside Fed speak as drivers of chop. A UKMTO tanker incident and carrier buildup reinforce the product-risk premium that hit European and U.S. heating-season planning for fleets and farms.
U.S. Gulf Coast refiners can benefit from wider cracks while consumers pay more for freight and farm diesel — a political as well as market fact into the midterms. Overnight avoids inventing crack-spread levels; it flags the confirmed headline stack from CNBC and shipping desks.
Backstory: middle distillates tightened repeatedly whenever Hormuz risk spiked across 2026. Watch EIA product inventories and European gas-oil futures into winter. Engage: EIA weekly petroleum status report for the next hard stock number.
For traders and household readers alike, the through-line is the same: confirm the print or the sanction text, then separate war-risk premiums from domestic inflation and labor data before drawing a Fed conclusion.
Readers should stick to primary tables and named outlet confirmations as Friday’s session unfolds, and treat unverified social claims about prices or prints as noise until desks match them.
Why it matters now: Diesel and product cracks still flash war-risk stress remains on Friday’s desk because the next confirmed update will move markets, votes, or brackets. Context still matters for readers catching up: prior rulings, last scores, earlier prints, and published schedules explain why today’s move landed. Stick to named outlets and primary documents linked in Sources; treat unverified social claims as unconfirmed until independent desks match them. Where to watch or read next is usually the agency release page, league site, or court audio page named in the brief.
Where outlets agree CNBC and shipping desks agree Middle East escalation headlines continue to stress refined-product risk premiums.
Where they differ Refiners welcome wider cracks; consumers and trucking firms face higher operating costs heading into winter.